Medicare Supplement and Medicare Advantage plans both fill gaps in Original Medicare, but they do it in opposite ways. One adds to Original Medicare. The other replaces it. In Connecticut the choice is also less permanent than it is in most states, which changes how you should think about it.
What Original Medicare leaves you to pay
Original Medicare is Part A and Part B, and it does not cover every healthcare expense. In 2026 the Part A hospital deductible is $1,736 per benefit period. Under Part B you pay a $283 annual deductible and then 20% of most services, with no yearly limit on what that 20% can add up to. Prescriptions are separate.
How a Medicare Supplement plan works
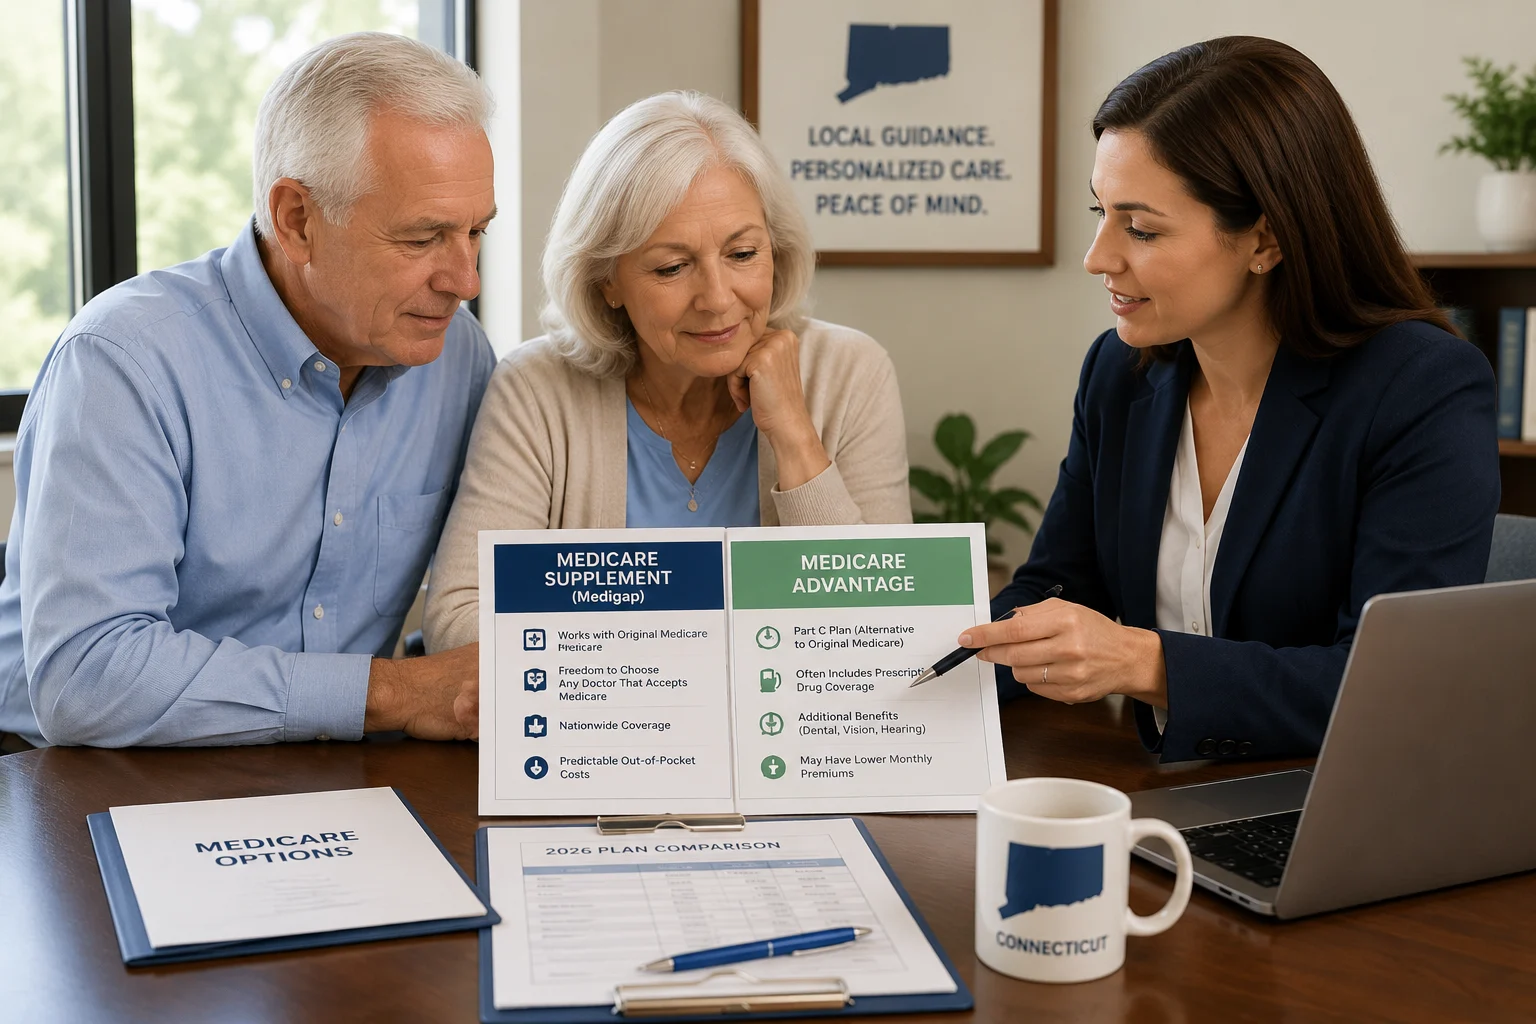
A Medicare Supplement plan, also called Medigap, pays after Medicare does. Depending on the plan letter, it covers some or all of the deductibles and coinsurance. The plan letters are standardized, so a Plan G from one company covers the same things as a Plan G from another. What differs is the premium and the service.
You can see any doctor or hospital in the country that accepts Medicare, with no network and no referrals. For retirees who travel or split the year between Connecticut and another state, that matters. You pay a monthly premium for the supplement on top of Part B, and you add a separate Medicare Part D plan for prescriptions.
How a Medicare Advantage plan works
A Medicare Advantage plan is a private plan that takes the place of Original Medicare. Many have low monthly premiums and include drug coverage along with some dental, vision and hearing benefits.
The trade-offs are a provider network, copays when you use care, and plan rules such as prior authorization. Every Medicare Advantage plan has an annual out-of-pocket limit for Part A and Part B services. For 2026 that limit can be no higher than $9,250, and plans may set it lower.
The Connecticut difference
In most states you can buy a Medigap policy without health questions only during a short window when you first enroll in Part B. After that, insurers can turn you down or charge more because of your health.
Connecticut law is different. Medigap policies here are guaranteed issue all year and community rated. An insurer can’t decline you for a health condition, and your premium isn’t based on your age. A Connecticut resident who starts in Medicare Advantage and later wants a supplement can make that move. That takes some pressure off the first decision.
Which one fits
A supplement tends to suit people who want to choose any doctor, who spend real time outside Connecticut, and who would rather pay a higher fixed premium than face variable costs when they get sick.
Medicare Advantage tends to suit people whose doctors are in the plan’s network, who want a lower monthly premium, and who value having drug, dental and vision coverage in one plan.
What to settle before you choose
Check whether your doctors and your hospital are in the network of any Medicare Advantage plan you’re considering. Run your prescriptions through each plan’s drug list. Think about how many weeks a year you spend out of state. Then compare what a bad year would cost under each option, not only the monthly premium.
The Jones Group compares Medicare supplement plans and Medicare Advantage plans for Connecticut residents. If you’re approaching 65 or reviewing your coverage for 2026, call us at (860) 529-3788 for a plan review.