An independent insurance agent works with multiple carriers, which means the agent can put plans from different companies side by side. Here is how to compare insurance carriers properly, step by step.
It starts with you, not the plans
Before looking at any plan, an agent needs four things from you: the doctors and hospitals you want to keep, the prescriptions you take with their dosages, a rough monthly budget, and how much financial risk you’re comfortable carrying. Someone who would rather pay more each month to avoid a large bill needs a different plan from someone who rarely sees a doctor.
Checking the prescriptions
Every plan has its own drug list, called a formulary. The same medication can sit on a low-cost tier in one plan and a high-cost tier in another, or be missing altogether. An agent runs your full prescription list through each plan and looks at the cost at the pharmacy you use, since pharmacy networks affect the price too.
Looking past the premium
The monthly premium is the easiest number to compare and the least useful one by itself. What matters is the total: premium, deductible, the copays for the care you actually use, and the out-of-pocket maximum.
A simple example shows why. A plan that costs $30 less each month saves $360 over the year. If its hospital copay is several hundred dollars higher, a single admission wipes out that saving. An agent works through both a normal year and a bad year for each option.
Confirming the network
Some plans let you see nearly any provider. Others limit you to a network, and networks change from year to year. An agent checks that your primary care doctor, your specialists, your preferred hospital and your pharmacy all participate in the plan for the coming year.
Comparing Medicare Supplement plans in Connecticut
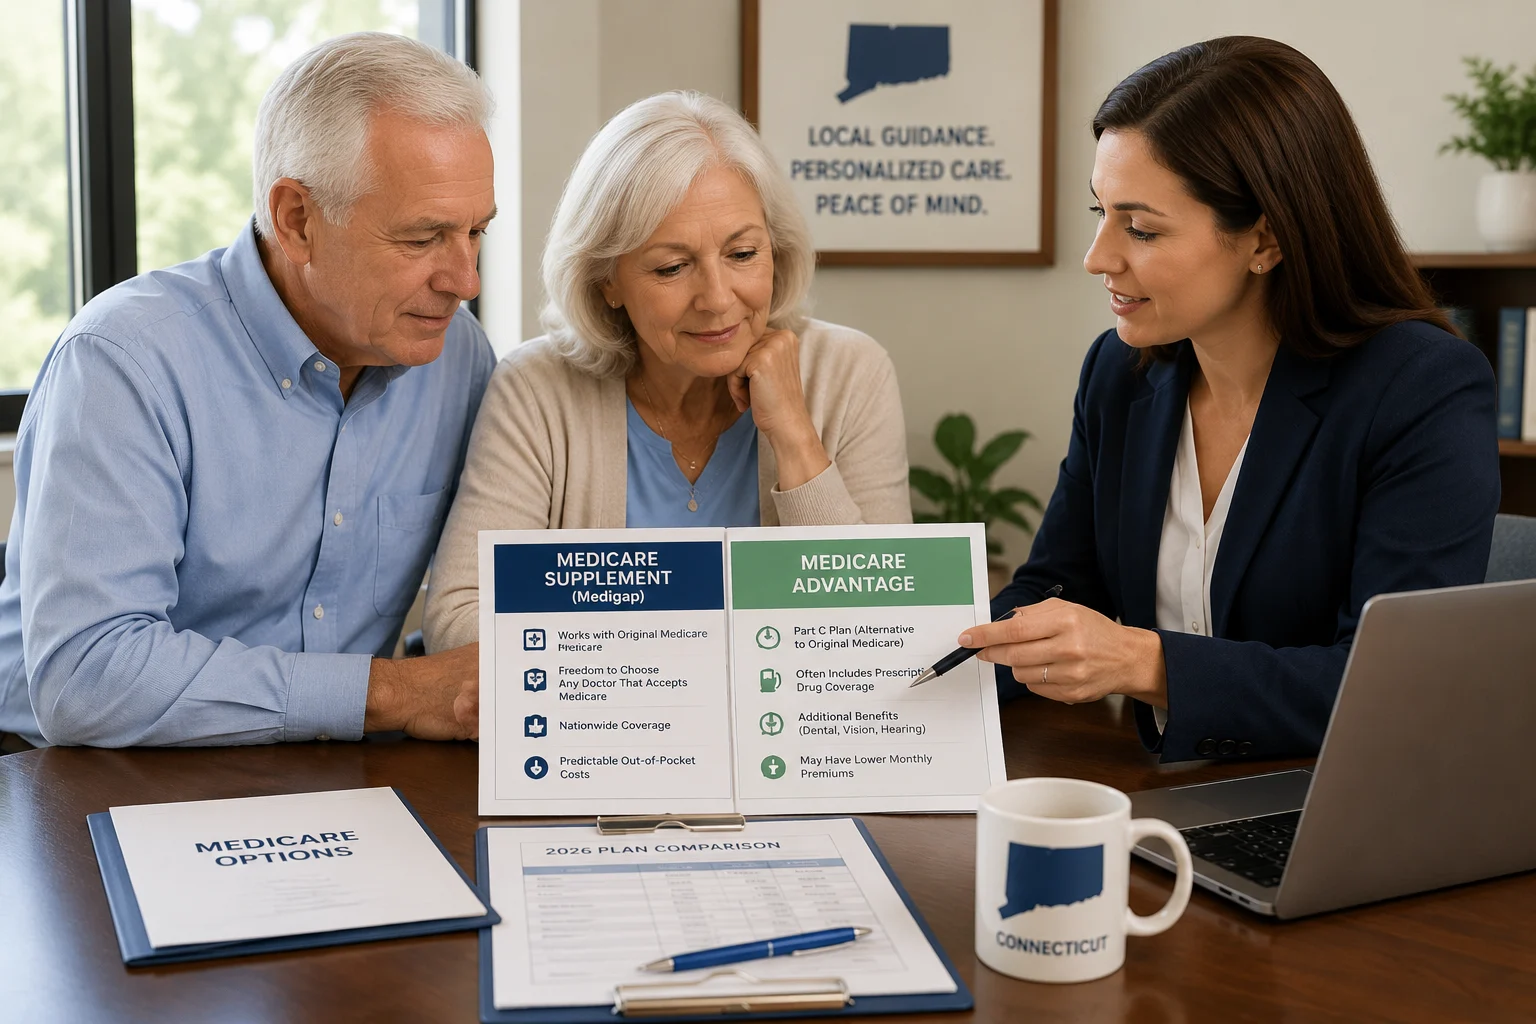
Medigap plans are standardized. A Plan G from one company covers exactly the same benefits as a Plan G from any other. So the comparison comes down to price, the company’s history of rate increases, and service. Connecticut makes it easier to act on what you find. Medigap plans here are community rated, so the price doesn’t depend on your age. They are also guaranteed issue at all times, so you can move to a lower-priced company later without health questions. The state’s CHOICES program publishes a chart of current Medigap rates by company, a useful check on any quote.
Comparing group plans for an employer
For a business, the method is the same with a few more inputs: how many employees enroll, how much the company contributes, and whether employees need family coverage. Each year an agent takes the group’s renewal and quotes it against other carriers, so the owner can see whether staying put still makes sense with their group plans.
Narrowing it down
After that work, most people are left with two or three plans that fit. The agent lays out the differences and you make the decision.
A question worth asking
No agent represents every company. Ask any agent which carriers they work with, so you know what the comparison covers. Agents who sell Medicare plans are required to tell you how many organizations they represent.
The Jones Group is an independent agency in Wethersfield. If you’d like us to compare carriers for your Medicare, health or life coverage, call (860) 529-3788.