
Turning 65 makes you eligible for Medicare. It doesn’t always enroll you in it. Whether you have to act, and by when, depends on two things: whether you’re already collecting Social Security, and whether you have health coverage through a current job.
Are you enrolled automatically?
If you started Social Security benefits at least four months before your 65th birthday, you’ll be enrolled in Part A and Part B automatically. Your card arrives in the mail.
If you haven’t started Social Security, nothing happens until you sign up. You do that through Social Security during your Initial Enrollment Period.
Your seven-month window
The Initial Enrollment Period begins three months before the month you turn 65 and ends three months after it. When you sign up within that window affects when coverage starts. Sign up before your birthday month and coverage begins that month. Sign up during your birthday month or the three months after, and coverage begins the month after you sign up.
The parts, with 2026 costs
Part A covers hospital care, and most people pay no premium for it. Part B covers doctor visits, outpatient care and preventive services. The standard Part B premium is $202.90 a month in 2026.
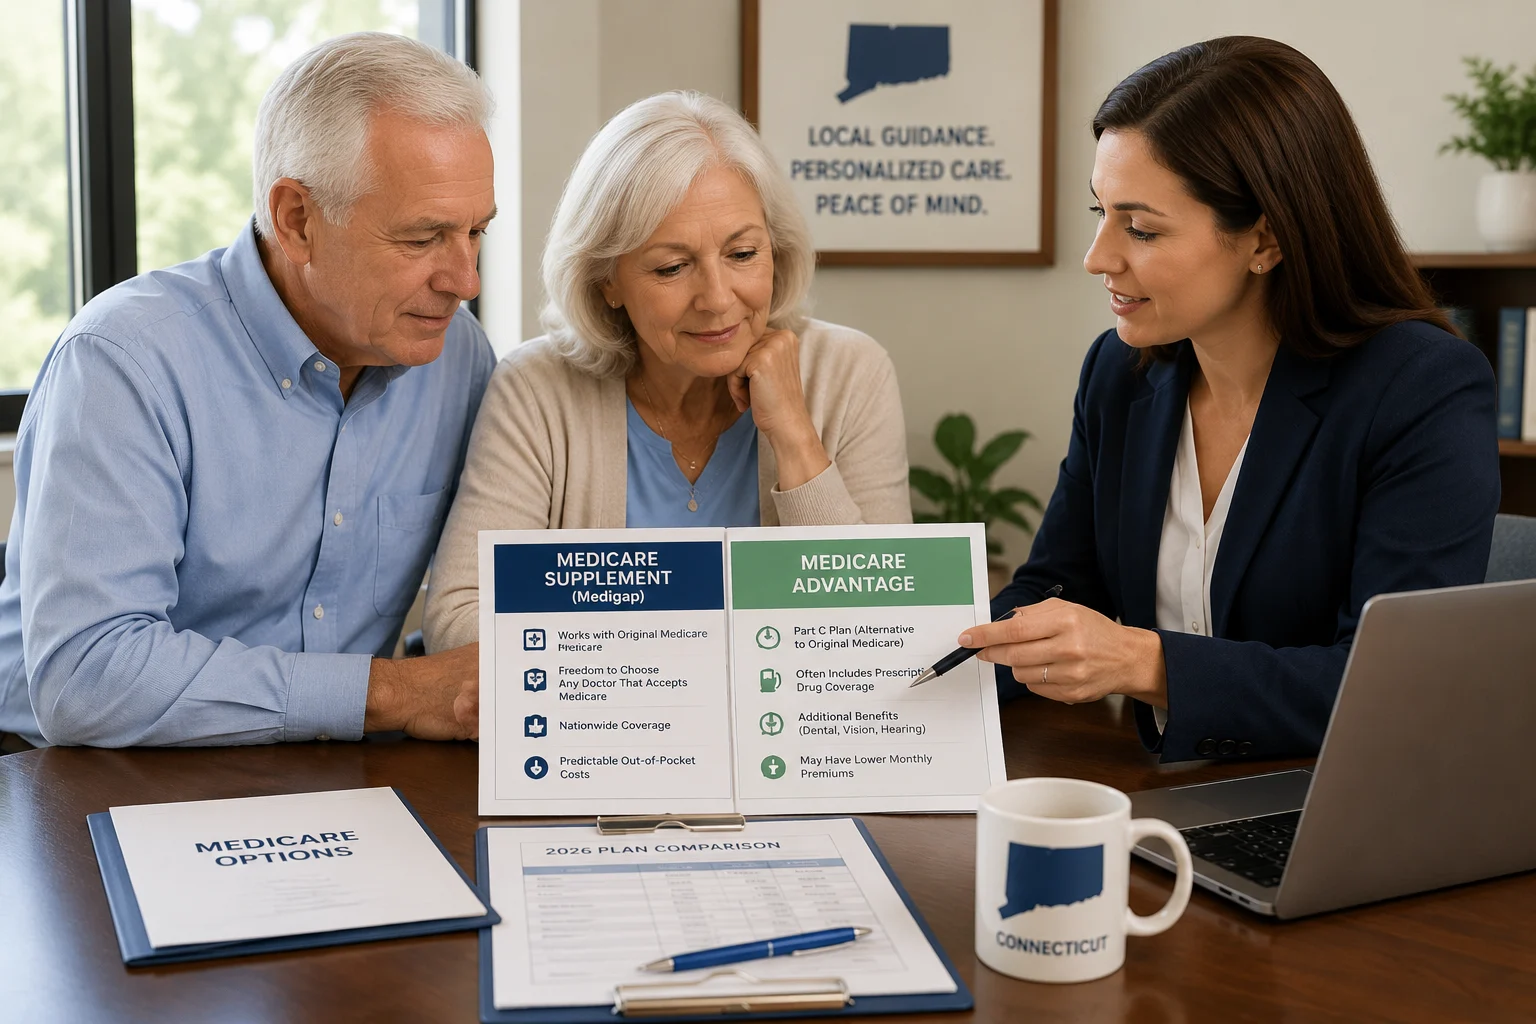
Part D covers prescription drugs through a private plan. Part C, Medicare Advantage, combines Parts A and B, and usually D, in one private plan with its own network.
If you’re still working
If you have health insurance through your own or your spouse’s current employer, and that employer has 20 or more employees, the employer plan pays first. You can usually delay Part B without a penalty, then sign up within eight months of the job or the coverage ending.
At an employer with fewer than 20 employees, Medicare pays first, so enrolling at 65 matters. We compare the two systems in health insurance vs. Medicare.
Mistakes that are expensive to fix
Missing the deadline is the most costly one. The Part B late penalty is 10% for every full 12 months you could have had Part B and didn’t. Someone who waits 24 months without other qualifying coverage pays a 20% penalty. In 2026 that turns the $202.90 premium into $243.50 a month, generally for as long as they have Part B.
Part D has its own penalty. Go 63 days or more without Medicare Part D or other creditable drug coverage, and you’ll pay an extra 1% of the national base premium, which is $38.99 in 2026, for each month you went without. It’s a small number that never goes away.
Other common mistakes: choosing a plan on premium alone, skipping drug coverage because you take no prescriptions today, and assuming Medicare covers dental, vision and long-term care.
A Connecticut advantage
In Connecticut, Medicare Supplement policies are guaranteed issue all year and community rated. You can’t be turned down for health reasons, and the premium doesn’t depend on your age. A special enrollment period isn’t required to buy one. That gives you more room to adjust later than residents of most states have.
Talk it through before you enroll
If you’re approaching 65 or helping a parent prepare, The Jones Group can go through the timing and the options with you. Call (860) 529-3788.