
If you’re in a Medicare Advantage plan and it isn’t working out, you don’t have to wait until fall to fix it. From January 1 through March 31 each year, the Medicare Advantage Open Enrollment Period lets you make a change.
It catches people off guard. Fall Open Enrollment ends December 7, and most people assume their choice is locked in for the year after that. For Medicare Advantage members, it isn’t.
Who can use it and what you can change
The window is only for people who are already in a Medicare Advantage plan. You can do one of two things: switch to a different Medicare Advantage plan, with or without drug coverage, or drop your plan, go back to Original Medicare, and join a separate Part D drug plan.
You get one change. Once it’s made, you’re set for the year unless you later qualify for a Special Enrollment Period. New coverage starts on the first of the month after the plan receives your request, so a change made in mid-February takes effect March 1.
There are things this window doesn’t do. If you have Original Medicare, it doesn’t let you join a Medicare Advantage plan, and it doesn’t let you switch from one standalone drug plan to another.
Signs your plan isn’t the right fit
The problems tend to show up in January, when the new plan year starts. Your doctor or a specialist has left the network. A prescription moved to a higher tier or dropped off the plan’s drug list. Copays went up. A treatment you need now requires prior authorization. Any one of these is a reason to compare.
Your plan mails an Annual Notice of Change each September that lists what is changing for the coming year. If you set it aside in the fall, it’s worth rereading now.
Going back to Original Medicare in Connecticut
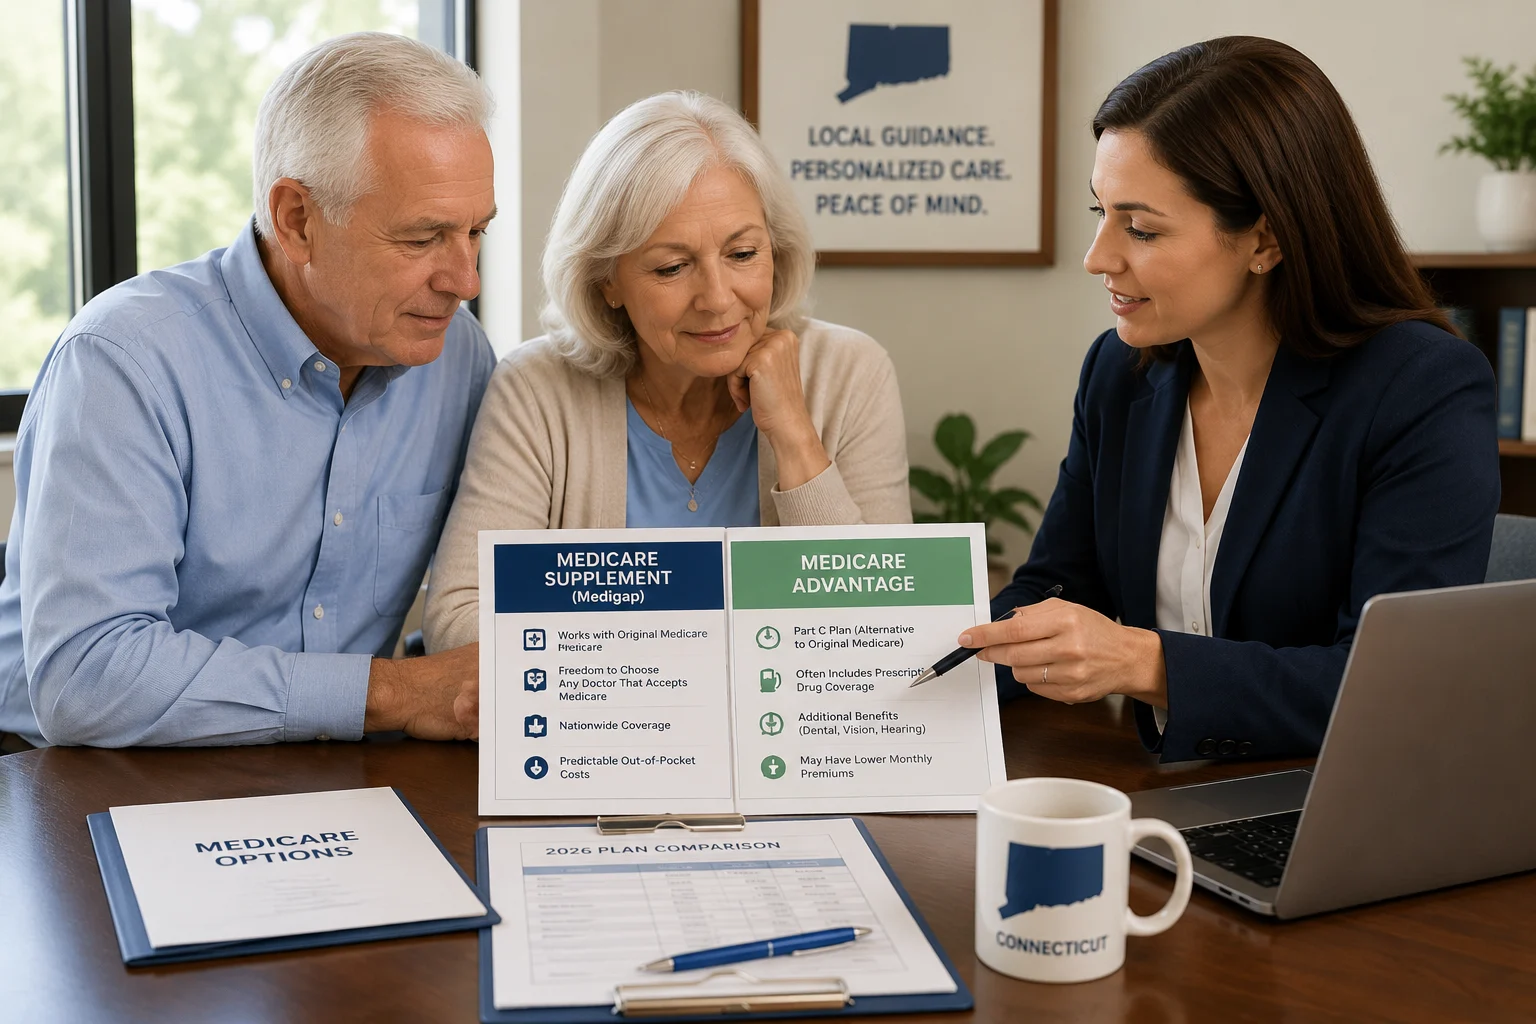
In most states, the risk in leaving Medicare Advantage is the Medigap policy. Outside of certain protected situations, insurers can review your health history and decline you or charge more. Connecticut is different. Under state law, Medigap policies here are guaranteed issue year-round and community rated, so you can buy one regardless of your health, and the premium isn’t based on your age. That makes returning to Original Medicare with a supplement a realistic option for Connecticut residents who find a network too limiting.
The cost side still needs a look. A Medigap policy and a Part D plan each carry a monthly premium on top of Part B. For some people that total is worth the predictability. For others, a different Medicare Advantage plan is the better move.
Before you switch
Have three things in front of you: your list of doctors, your prescriptions with dosages, and what you spent out of pocket last year. With those, comparing plans takes one conversation instead of guesswork.
The Jones Group reviews Medicare coverage year-round, not only during fall enrollment. If you want a second opinion before the March 31 deadline, call us at (860) 529-3788 or contact us.